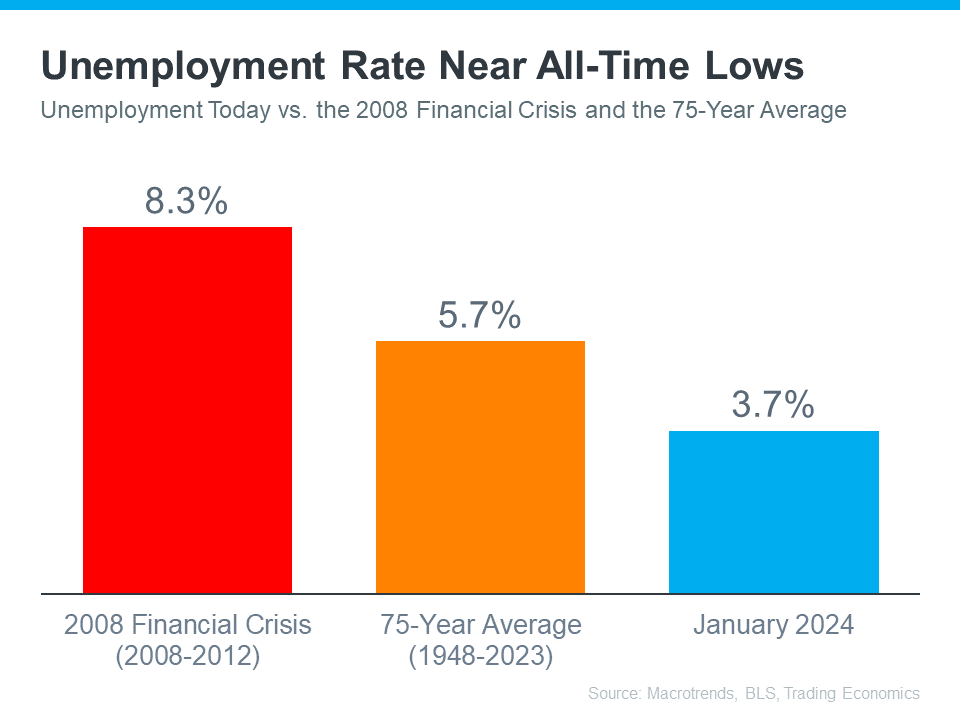March 29, 2024

What Every Homebuyer Should Know About Closing Costs In Connecticut
What Every Homebuyer Should Know About Closing Costs In Connecticut 


Before making the decision to buy a home, it's important to plan for all the costs you’ll be responsible for. While you're busy saving for the down payment, don't forget you’ll want to prep for closing costs too.

Here’s some helpful information on what those costs are and how much you should budget for them.

What Are Closing Costs?

A recent article from Bankrate explains:

“Closing costs are the fees and expenses you must pay before becoming the legal owner of a house, condo or townhome . . . Closing costs vary depending on the purchase price of the home and how it’s being financed . . .”

Simply put, your closing costs are the additional fees and payments you have to make at closing. According to Freddie Mac, while they can vary by location and situation, closing costs typically include:

  • Government recording costs
  • Appraisal fees
  • Credit report fees
  • Lender origination fees
  • Title services
  • Tax service fees
  • Survey fees
  • Attorney fees
  • Underwriting Fees

How Much Are Closing Costs?

According to the same Freddie Mac article mentioned above, they’re typically between 2% and 5% of the total purchase price of your home. With that in mind, here’s how you can get an idea of what you’ll need to budget.

Let’s say you find a home you want to purchase at today’s median price of $384,500. Based on the 2-5% Freddie Mac estimate, your closing fees could be between roughly $7,690 and $19,225.

But keep in mind, if you’re in the market for a home above or below this price range, your closing costs will be higher or lower.

Make Sure You’re Prepared To Close

Freddie Mac provides great advice for homebuyers, saying:

“As you start your homebuying journey, take the time to get a sense of all costs involved – from your down payment to closing costs.”

The best way to do that is by partnering with a team of trusted real estate professionals. That gives you a group of experts to help you understand how much you’ll need to save and what you’ll want to be prepped for. It also means you have go-to resources for any questions that pop up along the way.

Bottom Line

Planning for the fees and payments you'll need to cover when you're closing on your home is important. Partnering with a local real estate professional can give you the guidance and confidence you need throughout the process.
March 29, 2024

What's the Latestwith Mortgage Rates In Connecticut

What’s the Latest with Mortgage Rates In Connecticut


Recent headlines may leave you wondering what’s next for mortgage rates. Maybe you’d previously heard there were going to be cuts this year that would bring rates down. That refers to the Federal Reserve (the Fed) and what they do to their Fed Funds Rate. While cutting, or lowering, the Fed Funds Rate doesn’t directly determine mortgage rates, it does tend to impact them. But when the Fed met last week, a cut didn’t happen — at least, not yet. 

There are a lot of factors the Fed considered in their recent decision and most of them are complex. But you don’t need to be bogged down by those finer details. What you really want is the answer to this question: does that mean mortgage rates aren’t going to fall? Here’s what you need to know. 

Mortgage Rates Are Still Expected To Drop This Year

While it hasn’t happened yet, that doesn’t mean it won’t. Even Jerome Powell, the Chairman of the Fed, says they still plan to make cuts this year, assuming inflation cools:

“We believe that our policy rate is likely at its peak for this tightening cycle and that, if the economy evolves broadly as expected, it will likely be appropriate to begin dialing back policy restraint at some point this year.”

When this happens, history shows mortgage rates will likely follow. That means hope isn’t lost. As a recent article from Business Insider explains:

“As inflation comes down and the Fed is able to start lowering rates, mortgage rates should go down, too. . .”

What This Means for You

But you don’t necessarily want to wait for it to happen. Mortgage rates are notoriously hard to forecast. There are so many factors at play and any one of those can change the projections as the economy shifts. And it’s why the experts offer this advice. As Mark Fleming, Chief Economist at First American, says:

“Well, mortgage rate projections are just that, projections, not promises and don't forget how hard it is to forecast them. . . So my advice is to never try to time the market . . . If one is financially prepared and buying a home aligns with your lifestyle goals, then it could be the right time to purchase. And there's always the refinance option if mortgage rates are lower in the future.”

Basically, if you’re looking to move and trying to time the market, don’t. If you’re ready, willing, and able to move, it may still be worth it to do it now, especially if you can find the home you’ve been searching for.

Bottom Line

If you’re looking to buy a home, let’s connect so you have someone keeping you up-to-date on mortgage rates and helping you make the best decision possible.

March 28, 2024

Single Women Are Embracing Homeowership

Single Women Are Embracing Homeownership In Connecticut


In today's housing market, more and more single women are becoming homeowners. According to data from the National Association of Realtors (NAR), 19% of all homebuyers are single women, while only 10% are single men.

If you're a single woman trying to buy your first home, this should be encouraging. It means other people are making their dreams a reality – so you can too.

Why Homeownership Matters to So Many Women

For many single women, buying a home isn't just about having a place to live—it's also a smart way to invest for the future. Homes usually increase in value over time, so they’re a great way to build equity and overall net worth. Ksenia Potapov, Economist at First American, says:

“. . . single women are increasingly pursuing homeownership and reaping its wealth creation benefits.”

The financial security and independence homeownership provides can be life-changing. And when you factor in the personal motivations behind buying a home, that impact becomes even clearer.

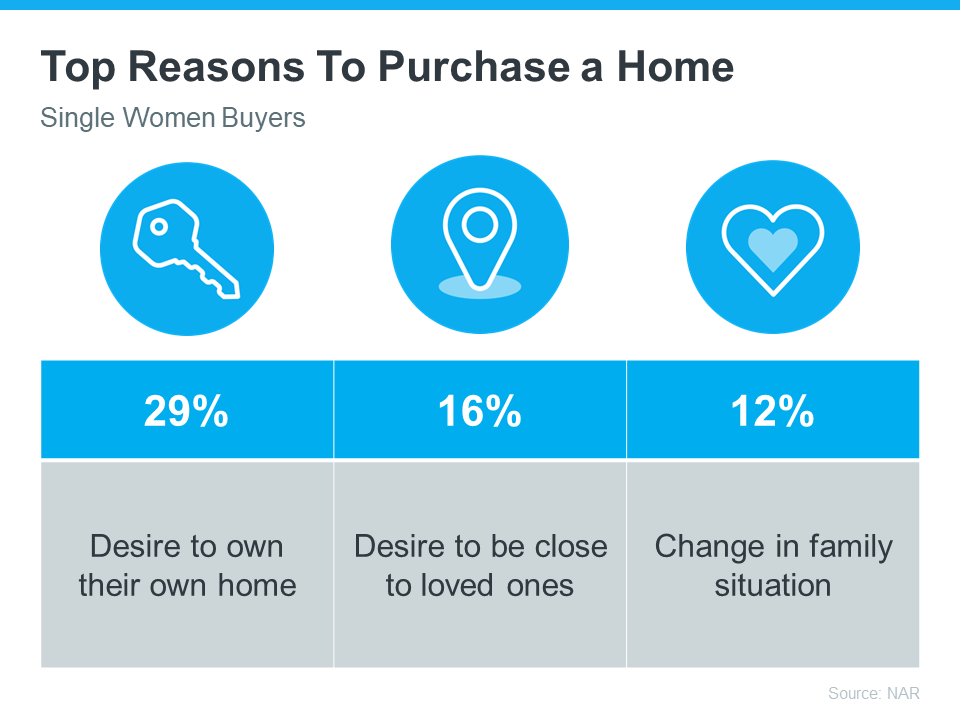
The same report from NAR shares the top reasons single women are buying a home right now, and the reality is, they’re not all financial (see chart below):

a blue and white diagram with white text


If any of these reasons resonate with you, maybe it’s time for you to buy too.

Work with a Trusted Real Estate Agent

If you’re a single woman looking to buy a home, it is possible, even in today’s housing market. You’ll just want to be sure you have a great real estate agent by your side.

Talk about what your goals are and why homeownership is so important to you. That way your agent can keep what’s critical for you up front as they guide you through the buying process. They’ll help you find the right home for your needs and advocate for you during negotiations. Together, you can make your dream of homeownership a reality.

Bottom Line

Homeownership is life-changing no matter who you are. Let's connect today to talk about your goals in the housing market.

Posted in Home Owner Tips
March 18, 2024

The Benefits of Downsizing When You Retire

The Benefits of Downsizing When You Retire In Connecticut


If you’re taking a look at your expenses as you retire, saving money where you can has a lot of appeal. One long-standing, popular way to do that is by downsizing to a smaller home.

When you think about cutting down on your spending, odds are you think of frequent purchases, like groceries and other goods. But when you downsize your house, you often end up downsizing the bills that come with it, like your mortgage payment, energy costs, and maintenance requirements. Realtor.com shares:

“A smaller home typically means lower bills and less upkeep. Then there’s the potential windfall that comes from selling your larger home and buying something smaller.”

That windfall is thanks to your home equity. If you’ve been in your house for a while, odds are you’ve built up a considerable amount of equity. And that equity is something you can use to help you buy a home that better fits your needs today. Daniel Hunt, CFA at Morgan Stanley, explains:

“Home equity can be a significant source of wealth for retirees, often representing a large portion of their net worth. . . . Retirement planning can be complex, but your home equity shouldn't be overlooked.”

And when you’re ready to use that equity to fuel your next move, your real estate agent will be your guide through every step of the process. That includes setting the right price for your current house when you sell, finding the home that best fits your evolving needs, and understanding what you can afford at today’s mortgage rate.

What This Means for You

If you’re thinking about downsizing, ask yourself these questions:

  • Do the original reasons I bought my current house still stand, or have my needs changed since then?
  • Do I really need and want the space I have right now, or could somewhere smaller be a better fit?
  • What are my housing expenses right now, and how much do I want to try to save by downsizing?

Then, meet with a real estate agent to get an answer to this one: What are my options in the market right now? A local real estate agent can walk you through how much equity you have in your house and how it positions you to win when you downsize.

Bottom Line

Want to save money in retirement? Consider downsizing – it could really help you out. When you’re ready, let’s connect about your goals in the housing market this year.

March 13, 2024

Why Access Is So Important When Selling Your House In Connecticut

Why Access Is So Important When Selling Your House In Connecticut


If you’re gearing up to sell your house in Connecticut this spring, one of the early conversations you’ll have with your agent is about how much access you want to give buyers. And you may not realize just how important it is to make your house easy to tour.

Spring is the peak homebuying season, so opening up your house to as many showings as possible can really help you capitalize on all the extra buyer activity we see at this time of year.

Since buyer competition ramps up in the spring, buyers are going to want to move fast to see your house once they find your listing. And, if they see it and fall in love with it at a time they know they’re competing with other buyers, you may be more likely to get the offer you’re looking for on your home.

It’s understandable you want to keep the disruptions to your own schedule to a minimum, and you may be stressed about having to keep it clean, but it’s worth it. As an article from Investopedia explains:

“If someone wants to view your house, you need to accommodate them, even if it inconveniences you. Clean and tidy the house before every single visit. A buyer won’t know or care if your house was clean last week. It’s a lot of work, but stay focused on the prize.”

To figure out what’s best for you, your agent will walk you through options like the ones below. This list breaks things down, starting with what’s most convenient for buyers and getting less buyer-focused as the list goes on:

  • Lockbox on the Door – A key is available via a lockbox, which makes it easy for agents to show the home to potential buyers. This gives the most flexibility because the key is on-site and convenient.
  • Providing a Key to the Home – An agent would have to stop by an office to pick up the key with this option. This is still pretty convenient for showings, but not quite as simple.
  • Open Access with a Phone Call – You allow a showing with just a phone call’s notice, which can be great for someone who sees your house while driving by.
  • By Appointment Only – This gives you a more advanced warning so you can get the house tidied up and be sure you have somewhere else you can go in the meantime. But it’s also a bit more restrictive.
  • Limited Access – You might go this route if you only want to have your house available on specific days or at certain times of day. But realize this is the most difficult and least flexible of the choices.

As an article from U.S. News Real Estate says:

“Buyers like to see homes on their schedule, which often means evenings and weekends. Plus, they want to be able to tour a home soon after they find it online, especially if they're competing with other buyers. If your home can be shown with little or no notice, more prospective buyers will see it. If you require 24 hours’ notice, they may choose to skip your home altogether.”

Your agent is going to help you find the right path forward based on your schedule and what’s working for other sellers in your area. And if you’ve got a hardline on granting buyers more access or have interested out of town buyers that just can’t be there in person, your agent will get creative and help you explore other options like video tours, virtual showings, and more.

Bottom Line

When it comes to selling your house, you want to be sure to get as much buyer activity as you can. Let’s connect to talk about which level of access helps make that possible.

March 12, 2024

Why There Won't Be a Recession That Tanks the Housing Market In Connecticut

Why There Won’t Be a Recession That Tanks the Housing Market In Connecticut


There’s been a lot of recession talk over the past couple of years. And that may leave you worried we’re headed for a repeat of what we saw back in 2008. Here’s a look at the latest expert projections to show you why that isn’t going to happen.  

According to Jacob Channel, Senior Economist at LendingTree, the economy’s pretty strong:

“At least right now, the fundamentals of the economy, despite some hiccups, are doing pretty good. While things are far from perfect, the economy is probably doing better than people want to give it credit for.”

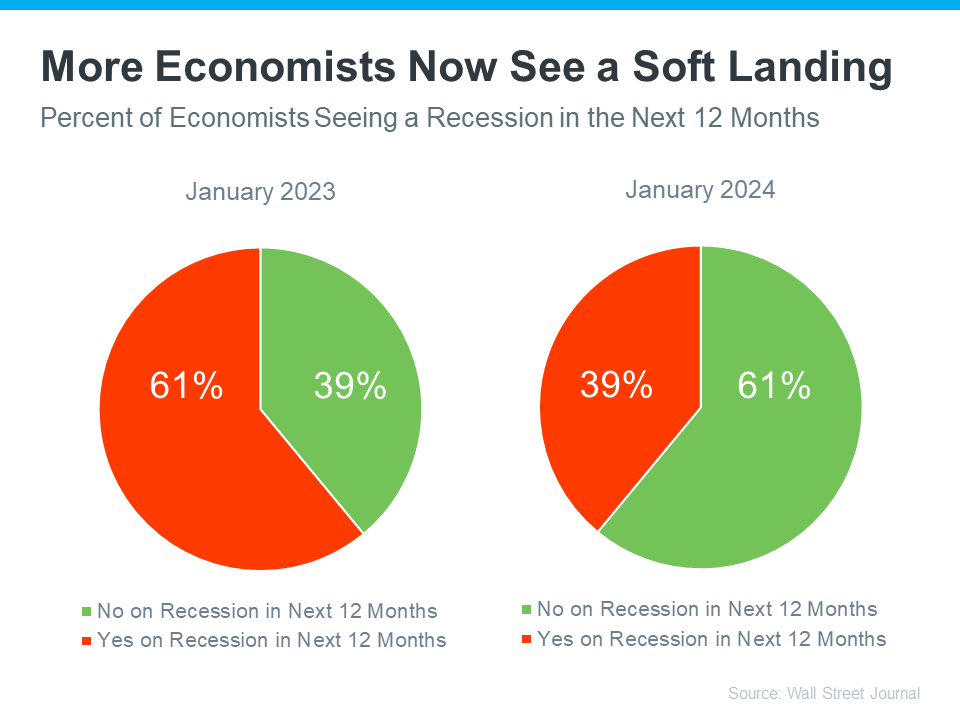
That might be why a recent survey from the Wall Street Journal shows only 39% of economists think there’ll be a recession in the next year. That’s way down from 61% projecting a recession just one year ago (see graph below):

a graph of the economic growth of the economy


Most experts believe there won’t be a recession in the next 12 months. One reason why is the current unemployment rate. Let’s compare where we are now with historical data from Macrotrends, the Bureau of Labor Statistics (BLS), and Trading Economics. When we do, it’s clear the unemployment rate today is still very low (see graph below):

 a graph of a graph showing the number of employment rate


The orange bar shows the average unemployment rate since 1948 is about 5.7%. The red bar shows that right after the financial crisis in 2008, when the housing market crashed, the unemployment rate was up to 8.3%. Both of those numbers are much larger than the unemployment rate this January (shown in blue).

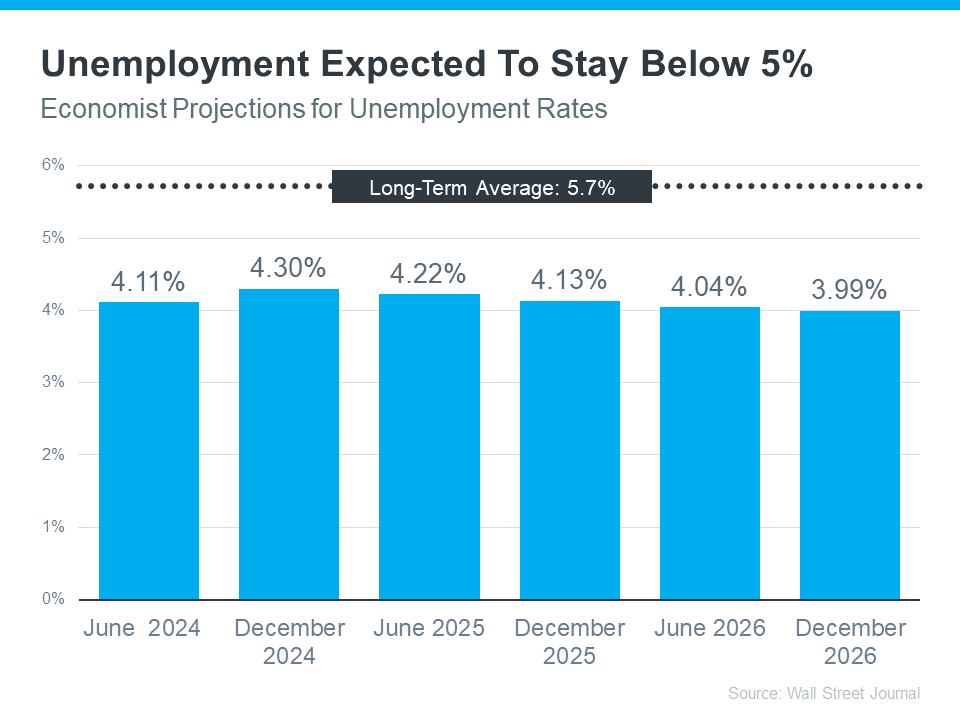
But will the unemployment rate go up? To answer that, look at the graph below. It uses data from that same Wall Street Journal survey to show what the experts are projecting for unemployment over the next three years compared to the long-term average (see graph below):

 a graph of blue bars


As you can see, economists don’t expect the unemployment rate to even come close to the long-term average over the next three years – much less the 8.3% we saw when the market last crashed.

Still, if these projections are correct, there will be people who lose their jobs next year. Anytime someone’s out of work, that’s a tough situation, not just for the individual, but also for their friends and loved ones. But the big question is: will enough people lose their jobs to create a flood of foreclosures that could crash the housing market?

Looking ahead, projections show the unemployment rate will likely stay below the 75-year average. That means you shouldn't expect a wave of foreclosures that would impact the housing market in a big way.

Bottom Line

Most experts now think we won't have a recession in the next year. They also don't expect a big jump in the unemployment rate. That means you don’t need to fear a flood of foreclosures that would cause the housing market to crash.

March 11, 2024

What To Know About Credit Scores Before Buying a Home In Connecticut

What To Know About Credit Scores Before Buying a Home In Connecticut


If you want to buy a home in Connecticut, you should know your credit score is a critical piece of the puzzle when it comes to qualifying for a mortgage. Lenders review your credit to see if you typically make payments on time, pay back debts, and more. Your credit score can also help determine your mortgage rate. An article from US Bank explains:

“A credit score isn’t the only deciding factor on your mortgage application, but it’s a significant one. So, when you’re house shopping, it’s important to know where your credit stands and how to use it to get the best mortgage rate possible.”

That means your credit score may feel even more important to your homebuying plans right now since mortgage rates are a key factor in affordability. According to the Federal Reserve Bank of New York, the median credit score in the U.S. for those taking out a mortgage is 770. But that doesn’t mean your credit score has to be perfect. The same article from US Bank explains:

“Your credit score (commonly called a FICO Score) can range from 300 at the low end to 850 at the high end. A score of 740 or above is generally considered very good, but you don’t need that score or above to buy a home.”

Working with a trusted lender is the best way to get more information on how your credit score could factor into your home loan and the mortgage rate you’re able to get. As FICO says:

“While many lenders use credit scores like FICO Scores to help them make lending decisions, each lender has its own strategy, including the level of risk it finds acceptable. There is no single “cutoff score” used by all lenders and there are many additional factors that lenders may use to determine your actual interest rates.”

If you’re looking for ways to improve your score, Experian highlights some things you may want to focus on:

  • Your Payment History: Late payments can have a negative impact by dropping your score. Focus on making payments on time and paying any existing late charges quickly.
  • Your Debt Amount (relative to your credit limits): When it comes to your available credit amount, the less you’re using, the better. Focus on keeping this number as low as possible.
  • Credit Applications: If you’re looking to buy something, don’t apply for additional credit. When you apply for new credit, it could result in a hard inquiry on your credit that drops your score.

Bottom Line

Finding ways to make your credit score better could help you get a lower mortgage rate. If you want to learn more, talk to a trusted lender.

May 30, 2023

The Best Time To Sell Your House Is When Others Aren't Selling In Connecticut

The Best Time To Sell Your House Is When Others Aren’t Selling In Connecticut


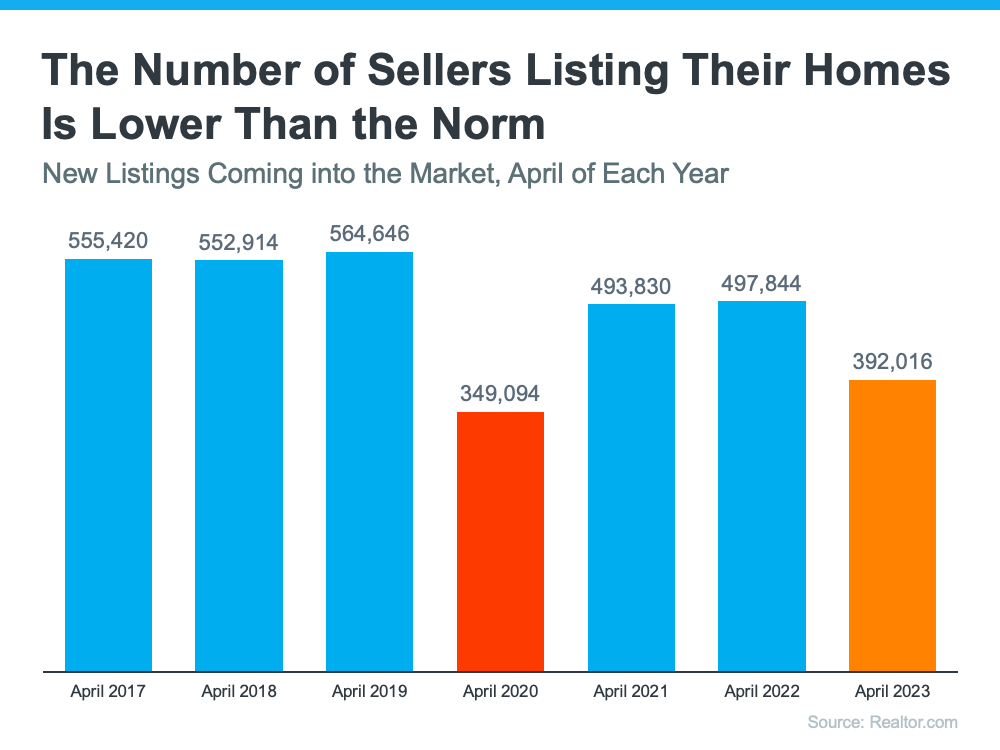
If you’re thinking about selling your house, you should know the number of homes for sale right now is low. That’s because, this season, there are fewer sellers listing their houses for sale than the norm.

Looking back at every April since 2017, the only year when fewer sellers listed their homes was in April 2020, when the pandemic hit and stalled the housing market (shown in red in the graph below). In more typical years, roughly 500,000 sellers add their homes to the market in April. This year, we saw fewer than 400,000 sellers entering the market in April (see graph below):

While there are a number of factors contributing to this trend, one thing keeping inventory low right now is that some homeowners are reluctant to move when the mortgage rate they have on their current house is lower than the one they could get today on their next house. It’s called rate lock.

As a recent survey from Realtor.com explains, 56% of people who are planning to sell in the next 12 months say they’re waiting for rates to come down.

While this wait-and-see approach is right for some sellers, it also creates an opening for more eager sellers to jump in now.

If your current house truly doesn’t fit your needs anymore and you’re ready to move, don’t miss this chance to stand out. When fewer sellers are putting their homes up for sale, buyers will have fewer options, so you set yourself up to get the most eyes possible on your house. That’s why your house could see multiple offers as buyers compete over the limited supply of homes for sale – especially if you price it right.

As Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), says:


“Inventory levels are still at historic lows . . . Consequently, multiple offers are returning on a good number of properties."

Bottom Line

If you’re ready to sell now, beat the competition before it comes onto the market. If you do, your house should stand out and could get multiple offers. Let's connect to get you market ready.

Posted in CT Seller Tips
May 29, 2023

Why Today's Housing Market Is Not About To Crash In Connecticut

Why Today’s Housing Market Is Not About To Crash In Connecticut


There’s been some concern lately that the housing market is headed for a crash. And given some of the affordability challenges in the housing market, along with a lot of recession talk in the media, it’s easy enough to understand why that worry has come up.

But the data clearly shows today’s market is very different than it was before the housing crash in 2008. Rest assured, this isn’t a repeat of what happened back then. Here’s why.

It’s Harder To Get a Loan Now

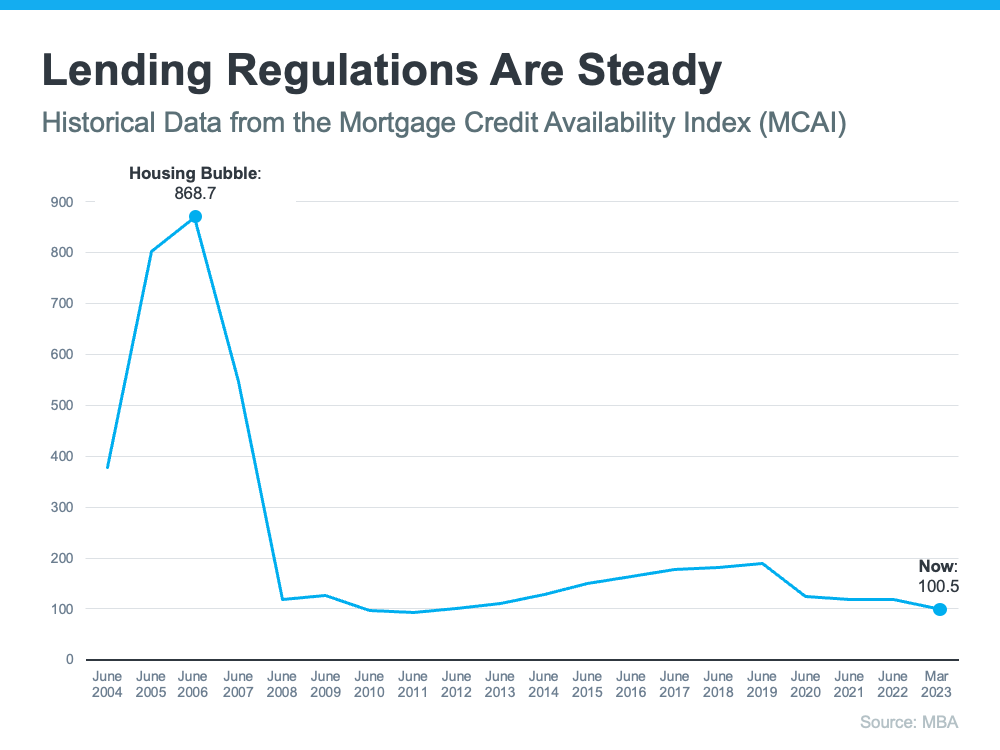
It was much easier to get a home loan during the lead-up to the 2008 housing crisis than it is today. Back then, banks had different lending standards, making it easy for just about anyone to qualify for a home loan or refinance an existing one. As a result, lending institutions took on much greater risk in both the person and the mortgage products offered. That led to mass defaults, foreclosures, and falling prices.

Things are different today as purchasers face increasingly higher standards from mortgage companies. The graph below uses data from the Mortgage Bankers Association (MBA) to show this difference. The lower the number, the harder it is to get a mortgage. The higher the number, the easier it is.

Unemployment Recovered Faster This Time

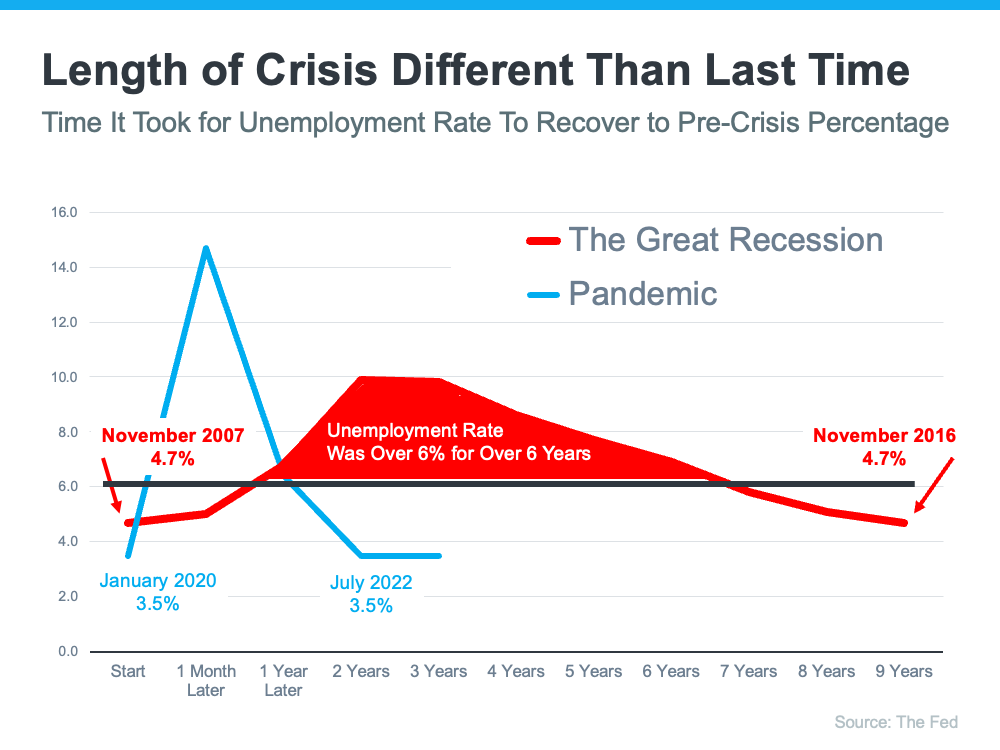
While the pandemic caused unemployment to spike over the last couple of years, the jobless rate has already recovered back to pre-pandemic levels (see the blue line in the graph below). Things were different during the Great Recession as a large number of people stayed unemployed for a much longer period of time (see the red in the graph below):

Here’s how the quick job recovery this time helps the housing market. Because so many people are employed today, there’s less risk of homeowners facing hardship and defaulting on their loans. This helps put today’s housing market on stronger footing and reduces the risk of more foreclosures coming onto the market.

There Are Far Fewer Homes for Sale Today

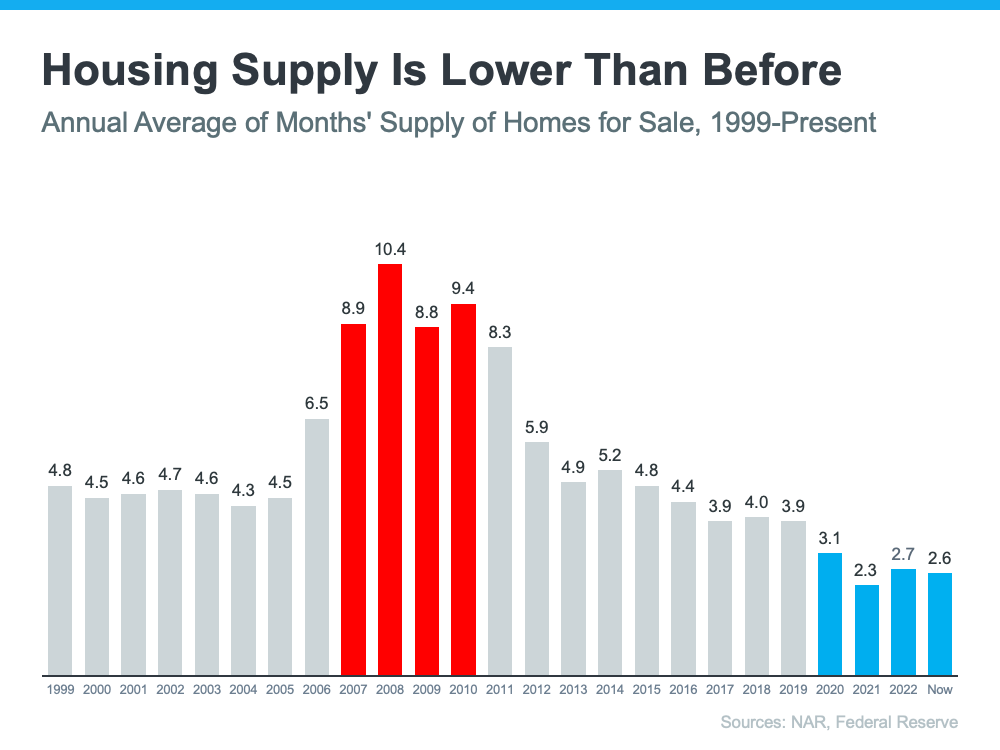
There were also too many homes for sale during the housing crisis (many of which were short sales and foreclosures), and that caused prices to fall dramatically. Today, there’s a shortage of inventory available overall, primarily due to years of underbuilding homes.

The graph below uses data from the National Association of Realtors (NAR) and the Federal Reserve to show how the months’ supply of homes available now compares to the crash. Today, unsold inventory sits at just a 2.6-months’ supply. There just isn’t enough inventory on the market for home prices to come crashing down like they did in 2008.

Equity Levels Are Near Record Highs

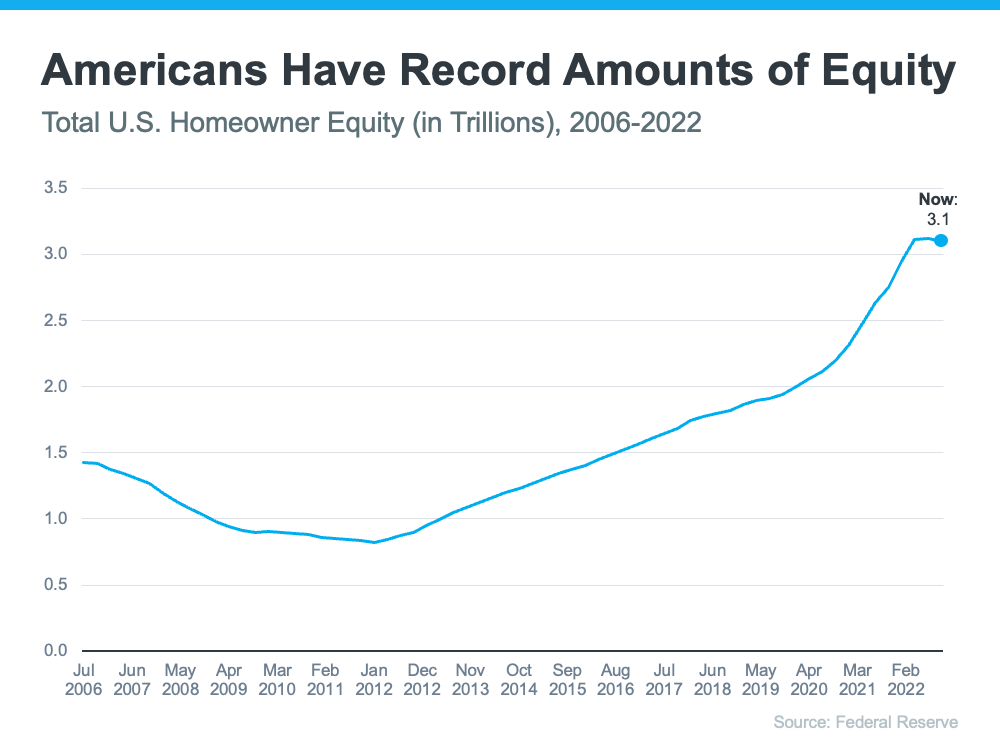
That low inventory of homes for sale helped keep upward pressure on home prices over the course of the pandemic. As a result, homeowners today have near-record amounts of equity (see graph below):

And, that equity puts them in a much stronger position compared to the Great Recession. Molly Boesel, Principal Economist at CoreLogic, explains: 

“Most homeowners are well positioned to weather a shallow recession. More than a decade of home price increases has given homeowners record amounts of equity, which protects them from foreclosure should they fall behind on their mortgage payments.”

Bottom Line

The graphs above should ease any fears you may have that today’s housing market is headed for a crash. The most current data clearly shows that today’s market is nothing like it was last time.

May 26, 2023

It May Be Time To Consider a Newly Built Home In Connecticut

It May Be Time To Consider a Newly Built Home In Connecticut


If you’re looking to buy a house, you may find today’s limited supply of homes available for sale challenging. When housing inventory is as low as it is right now, it can feel like a bit of an uphill battle to find the perfect home for you because there just isn’t that much to choose from. If you need to open up your pool of options, it may be time to consider a newly built home.

 According to the latest data from the U.S. Census, there’s positive news when it comes to new home construction. When you look at the first three months of this year, you’ll find:


  • More new homes were completed and are ready to sell. This gives you more move-in-ready options for your search.
  • Builders broke ground and started construction on more single-family homes. This means there are more homes intended for one household in the beginning stages of construction, allowing you the opportunity to customize one to your liking.
  • The number of permits for building new single-family homes ticked up. This shows builders are ramping up to start on even more home construction soon. 

And, while this is all good news for broadening your options for your home search, there are other perks that come with considering a newly built home.

Customization 

When you buy a new home under construction, you can tailor it to your unique needs and taste. Bankrate says: 


“Building means customizing. . . . instead of wishing your home had a certain kind of flooring, a sunroom or some other special amenity, you’ll be able to tailor the property to your exact needs.” 
Brand New Everything 

Another perk of a new home is that nothing in the house is used. It’s all brand new and uniquely yours from day one.

Minimal Repairs

And, because everything is new, you’ll likely find there are fewer maintenance and repair needs up front. As Realtor.com explains:  

“. . . if something does go wrong with your new home, not only are there likely some manufacturer warranties in place, but many builders also include additional home warranties . . .” 
Energy Efficiency 

Lastly, building a home gives you the opportunity to incorporate more energy-efficient options that can help lower your costs over time – which can feel especially important when inflation’s raising many of the costs around you.

Bottom Line

If you’re having trouble finding your dream home in today’s market, it may be time to consider newly built homes as an option. Let’s connect so you have an expert on your side to help you explore what’s available in our local area.